Percentages remove size, so you can compare a 50m company with a 900m one.
From first principles
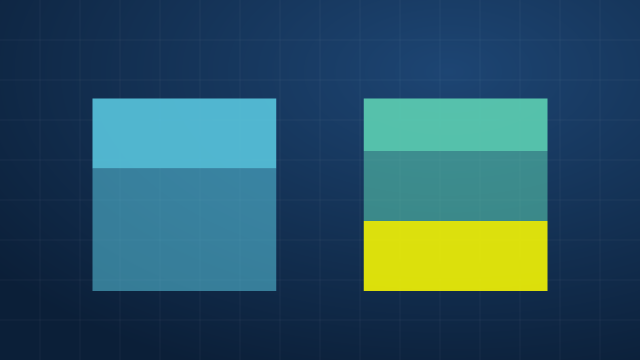
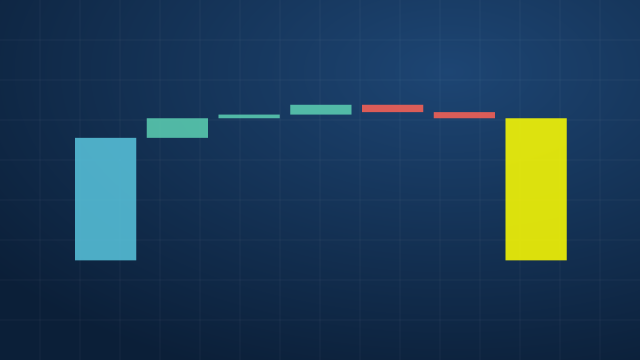
Raw numbers cannot compare a small firm with a large one, or a firm with itself ten years ago. Scaling every income statement line by revenue turns it into "cents per unit of sales": the cost structure laid bare. On the balance sheet, scaling by total assets shows how the firm is financed and what it invests in.
Worked example
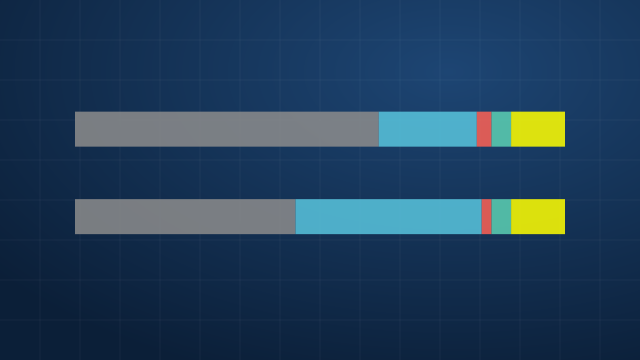
Two companies both earn 11 cents per unit of revenue. Company A spends 62% on cost of sales and 20% on operating expenses: a low-margin, lean operator. Company B spends only 45% on cost of sales but 38% on operating expenses: a premium product with heavy selling and R&D spending. If revenue falls 10%, which one's profit suffers more? The one with more fixed costs, likely B's operating expenses, which do not shrink with sales.
Exam traps
- Vertical common-size divides by a total within one period; horizontal analysis compares each line with a base year.
- A rising cost-of-sales percentage can mean higher input prices or lower selling prices: the common-size number alone does not tell you which.
- Common-size statements are a starting point; the explanation needs the notes and industry context.
Questions people ask
What is the difference between vertical and horizontal analysis?
Vertical (common-size) analysis divides every line by a base in the same year, such as revenue or total assets. Horizontal analysis tracks how one line changes across years. Using both shows structure and trend.
Why is common-size analysis useful for comparing companies?
It strips out size. A company with revenue of 10 billion and one with 100 million can be compared line by line once everything is a percentage of revenue.
What should you look for first in a common-size income statement?
Gross margin and the big expense lines. A shrinking gross margin points to pricing or input costs; rising overheads as a share of sales point to weaker cost control.