Comprehensive income = net income + other comprehensive income = all non-owner changes in equity.
From first principles
Equity changes for two reasons: transactions with owners (issuing shares, dividends, buybacks) and everything else. "Everything else" is comprehensive income.
Most of it passes through the income statement as net income. But standard-setters decided some gains and losses are too volatile, or not yet realised, to belong in reported profit. They go to other comprehensive income (OCI) and accumulate in a reserve within equity. Common examples:
- foreign currency translation adjustments on foreign subsidiaries;
- some pension remeasurements;
- gains and losses on the effective portion of hedges of future cash flows;
- fair value changes on certain debt investments held at fair value through OCI;
- revaluation surpluses on PP&E under IFRS.
Worked example
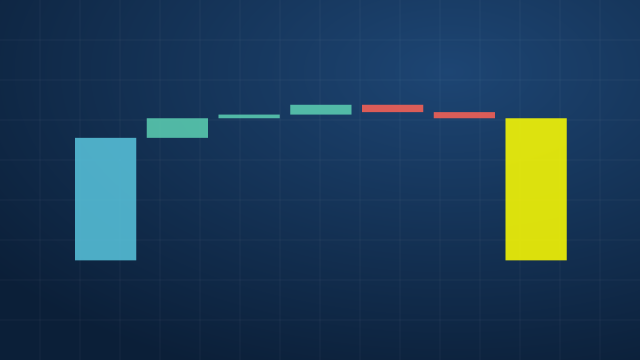
Net income 500. The euro strengthened against the parent's currency, adding 40 to the value of a euro subsidiary; a pension remeasurement cost 15. OCI = 40 − 15 = 25. Total comprehensive income = 525. Equity also falls by dividends of 200, which are not part of comprehensive income because they are a transaction with owners.
Exam traps
- Dividends and share issues are never in comprehensive income.
- Some OCI items are later recycled into profit when realised (hedges of future cash flows are the classic case); others never are.
- Comparing return on equity across firms can be distorted if one firm's losses sit in OCI.
Questions people ask
What goes into other comprehensive income?
Gains and losses that standard setters keep out of profit for now: currency translation of foreign subsidiaries, certain pension remeasurements, some fair value changes on investments and the effective part of hedges of future cash flows.
What does recycling mean?
Moving a gain or loss that sat in OCI into profit when it is finally realised, for example when the hedged transaction happens. Under IFRS some OCI items are recycled and some never are.
Why should analysts look at comprehensive income?
Because large losses can sit in OCI without ever touching net income. Comparing companies on comprehensive income shows the full change in owners' wealth from things other than dealings with owners.