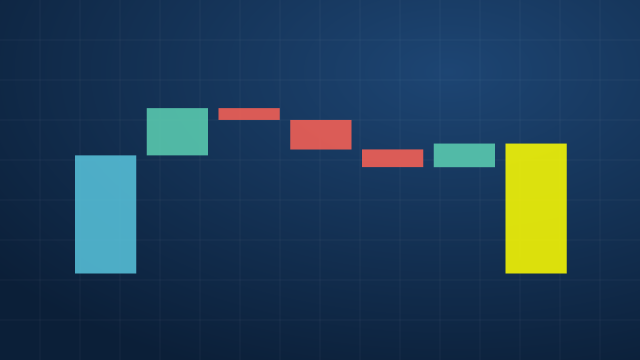
CFO = net income + non-cash expenses − non-cash gains − increases in operating assets + increases in operating liabilities.
From first principles
Net income includes items that are not cash, and misses cash that is not income. To get from one to the other:
- Add back non-cash expenses (depreciation, amortisation, impairments): they reduced profit but no cash left.
- Remove gains, add back losses on selling assets: the cash from the sale belongs in investing, so its gain must come out of operating.
- Adjust for working capital. If receivables rose, some revenue was not collected: subtract the increase. If inventory rose, cash went into the shelves: subtract. If payables rose, you did not pay some bills yet: add.
The rule of thumb: an increase in an operating asset uses cash (subtract); an increase in an operating liability provides cash (add).
Worked example
Net income 100, depreciation 40, gain on sale of equipment 10, receivables up 25, inventory up 15, payables up 20. CFO = 100 + 40 − 10 − 25 − 15 + 20 = 110.
The direct method reaches the same CFO by listing cash receipts and payments; IFRS encourages it but most firms use the indirect method.
Exam traps
- Gains are subtracted even though they increased profit.
- The sign of the working-capital adjustment is the most common error: rising receivables reduce CFO.
- Amortisation of a bond discount is a non-cash expense: add it back.
Questions people ask
Why add depreciation back to net income?
Because it reduced profit without any cash leaving. The cash went out years earlier, when the asset was bought, and was shown then as investing cash flow.
How do working capital changes affect operating cash flow?
A rise in an operating asset such as receivables or inventory uses cash, so it is subtracted. A rise in an operating liability such as payables keeps cash in the business, so it is added.
Do direct and indirect methods give different operating cash flow?
No. The total is the same; only the presentation differs. The direct method lists cash received and paid; the indirect method reconciles from net income. Most companies use the indirect method.