MV = PY. Nominal rate ≈ real rate + expected inflation.
From first principles
The quantity equation: money × velocity (how often each unit is spent) = price level × real output. It is an identity. It becomes a theory with one assumption: if velocity and real output are roughly stable, then money growth shows up as inflation. That holds well over long periods and in high-inflation countries, and poorly over short ones.
Why hold money at all? Three motives: transactions (paying for things), precaution (emergencies) and speculation (holding money when other assets look risky). Higher interest rates raise the cost of holding money, so money demand falls.
The Fisher effect. Lenders care about real returns: what their money will buy. If they expect 3% inflation and want a 2% real return, they demand about 5% nominal. So nominal rates move one-for-one with expected inflation. A further premium compensates for uncertainty about inflation.
The costs of inflation
- Expected inflation has modest costs: changing prices (menu costs) and holding less cash (shoe-leather costs).
- Unexpected inflation is worse: it redistributes wealth from lenders to borrowers, and uncertainty makes long-term planning and lending more expensive.
Worked example
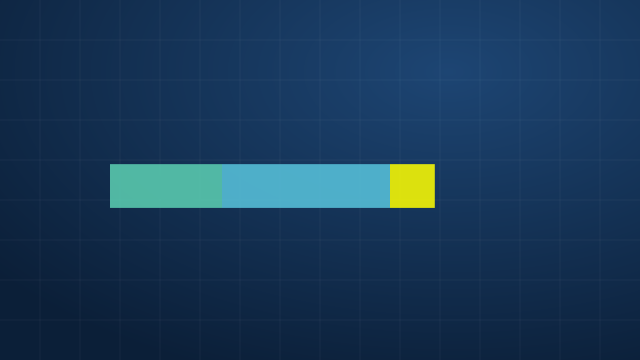
A 10-year bond yields 5.8%. With a 2% real rate and 3% expected inflation, the remaining 0.8% is compensation for inflation risk. If expected inflation rises to 4%, the yield should rise to about 6.8%.
Exam traps
- The quantity theory is a long-run relationship.
- The Fisher effect uses expected, not realised, inflation.
Questions people ask
What is the equation of exchange?
Money supply times its velocity equals the price level times real output (MV = PY). If velocity and output are stable, faster money growth means faster inflation.
What is the Fisher effect?
Nominal interest rates move with expected inflation, so the real rate stays roughly unchanged. A nominal rate is approximately the real rate plus expected inflation.
Why is inflation costly even if it is expected?
People hold less cash, prices must be changed more often, taxes based on nominal gains rise in real terms, and relative prices become harder to read. Unexpected inflation adds a transfer from lenders to borrowers.